Navigating 2026 tax changes: Expert insights from CPA Ontario's Tax Immersion Program
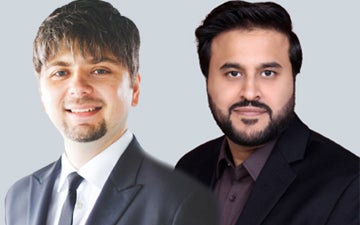
CPA Ontario's Tax Immersion Program equips CPAs with the skills to thrive in an evolving Canadian tax landscape. A Q&A with CPAs Alex Garber & Haroon Khan
THE 2026 tax year brings a fresh set of planning opportunities and compliance challenges for Chartered Professional Accountants (CPAs), and staying current is essential to delivering the advice clients need
To help navigate the changing Canadian tax landscape, CPA Ontario's Tax Immersion Program continues under the expert guidance of Alex Garber, CPA, CA, MTax, and Haroon Khan, CPA, CA. Alex is an award-winning professor at the Schulich School of Business at York University and an independent tax advisor. Haroon is a seasoned tax professional with over 15 years of experience advising private corporations on tax planning, mergers & acquisitions, and cross-border structuring.
Their combined expertise provides a well-rounded perspective on the latest tax developments, and we asked them to share their thoughts on the 2026 tax planning season.
Q: What are some of the incentives that could help with tax planning?
Haroon Khan: When we think about tax planning, we often focus on an immediate deduction or credit. But some of the most effective strategies are those that manage tax over a taxpayer's lifetime and facilitate the eventual transfer of wealth.
Life insurance planning is one example. Certain exempt life insurance policies can provide tax-deferred growth during the policyholder's lifetime while also forming an important part of an estate plan. Where appropriate, corporate-owned life insurance can also provide significant estate-planning advantages.
For business owners, estate freezes remain an important tool: by freezing the current value of the business and bringing the next generation into the ownership structure early, future growth can accrue to the next generation while the founder retains control. Starting this planning early is often critical for businesses continuing to appreciate significantly.
There are also succession-planning opportunities emerging from recent legislative changes. Genuine intergenerational transfers can help transition a family business to the next generation, while employee ownership trusts (EOTs) can facilitate a sale to employees. The eligibility requirements and transaction structure need to be considered well before the transaction takes place.
Lifetime capital gains exemption planning should also remain on the radar. Planning is not simply about claiming the exemption on sale — it can involve crystallization strategies, ensuring shares continue to qualify as QSBC shares, and purifying the corporation well in advance.
For businesses making investments, the capital cost allowance regime and enhanced expensing measures can create meaningful opportunities, particularly when timing significant investments in equipment or technology. It is important to note that in 2026, many of the proposals introduced in prior years were enacted into law, making these measures particularly relevant for current-year tax planning.
Finally, SR&ED remains a major planning opportunity for eligible businesses, particularly following the significant changes to the program that were legislated in 2026. CPAs should ensure clients identify qualifying projects early, maintain appropriate documentation, and consider the interaction between SR&ED incentives and regular income tax deductions.
Alex Garber: A few updates are worth flagging. The Employee Ownership Trust exemption, which allows up to $10 million of capital gains to be exempt from tax on a qualifying sale to an EOT, was originally a temporary measure but has now been made permanent — removing the pressure that had been pushing owners toward a specific window to transact.
The lifetime capital gains exemption is also expected to rise again, to $1.275 million for 2026, continuing recent years' trend. And there have been further enhancements to the capital cost allowance system, with the "re-accelerated investment incentive" applying to eligible property acquired in 2025 and onward, another reason to revisit the timing of planned capital expenditures.
Q: Trust reporting rules continue to evolve. What are the key compliance challenges CPAs are seeing, and what strategies can help clients meet their obligations?
Haroon Khan: The biggest challenge with the trust reporting rules is that the analysis often begins with a deceptively simple question: "Is there a trust?" In practice, many arrangements don't look like traditional trusts — CPAs encounter family members, nominees, jointly held property, corporations, and arrangements where legal ownership differs from beneficial ownership.
The rules have also evolved. In 2026, the legislation clarified the concept of a "deemed trust," including rules under subsection 150(1.3) and exceptions under subsection 150(1.31). Certain informal arrangements where legal title is held by one party for the benefit of another will also be subject to reporting again for taxation years ending on or after December 31, 2026 — a reminder that trust reporting is not a static area of compliance.
A practical approach is to make trust reporting part of the annual client review. Rather than simply asking whether a client has a trust, ask targeted questions about property or accounts held for someone else, joint ownership arrangements, and nominee relationships. Ultimately, trust reporting is a fact-finding exercise, not simply a tax return exercise.
Alex Garber: One specific change practitioners need to be ready for is the return of reporting for so-called "bare trusts." now referred to as “deemed trusts” under the new terminology. These arrangements were previously exempt from T3 reporting, but that exemption is ending – Deemed trusts will now have to be reported for the December 31, 2026 year-end. This is likely to increase the workload for CPAs come March 2027, so it's worth getting ahead of client conversations now rather than waiting for filing season.
Q: What other tax areas should CPAs prioritize in their practice? Are there emerging compliance requirements or changes that warrant attention?
Haroon Khan: Beyond trust reporting, CPAs should keep a close eye on the mandatory disclosure rules for reportable and notifiable transactions, as well as reportable uncertain tax treatments. These carry significant penalties for non-compliance and require practitioners to think critically about transaction-level tax risk.
International tax awareness is also becoming essential for every CPA, even those who don't specialize in it. The expectation isn't that every CPA solve complex cross-border issues, but that they identify when one exists and know when to bring in a specialist. For example, a Canadian client who is also a U.S. citizen may have significant U.S. filing obligations involving foreign corporations, trusts, or financial accounts — and failure to identify those can result in substantial Canadian and U.S. penalties. A simple intake question such as "Are you, your spouse, or any of the owners U.S. citizens or residents of another country?" can uncover issues that warrant specialist advice.
Finally, digital assets, including cryptocurrency and NFTs, remain an area where client activity is evolving rapidly. Although CRA has issued guidance, practical issues around classification, record-keeping, and valuation can still be challenging, and clients should understand that the absence of a straightforward answer doesn't mean there's no tax obligation.
Ultimately, one of the most important skills for CPAs today is not knowing every area of tax — it is knowing what they know, what they do not know, and when another specialist needs to be brought into the conversation.
Alex Garber: Beyond the legislative changes, one trend worth watching is the continued development of AI-based tools, which are becoming more refined and widespread in tax work. CPAs who invest time now in understanding how these tools fit into their practice will be better positioned as adoption accelerates.
CPA Ontario Tax Immersion Program
To help navigate these complex changes, CPA Ontario's Tax Immersion Program offers comprehensive tax education through multiple learning streams.
Led by instructors with decades of experience, the program offers four distinct pathways to equip CPAs with the knowledge and tools to thrive in an evolving tax environment:
- Tax Immersion Program (Personal & Corporate Tax) — Essential tax principles in income tax, capital transactions and shareholder taxation
- Part 2 (Income Tax & Specific Topics) — Advanced income tax concepts and specialized areas such as commodity tax, real estate, and estates and trusts
- Owner-Managed Structures (Tax & Accounting for Small Businesses) — Focused on the unique needs of small business taxation and accounting
- New Part 4 (Advanced) — Built for experienced CPAs ready to research, advise, and execute complex tax transactions, combining legislation, jurisprudence, professional judgment, and transaction execution.
What You'll Learn
These programs go beyond updates and give you valuable insights into relevant nuances for Ontario tax. This holistic approach ensures you're prepared to handle your clients' or organization's tax needs across all business structures and complexity levels.
Through these comprehensive learning streams, you'll enhance your tax knowledge and apply your learning effectively. You'll be well-equipped to address and strategically leverage these tax updates as well as provide exceptional tax advice whether you're working with individuals, corporations, or owner-managed businesses.
Get ready for the 2026 tax season: Register today.
Alex Garber, CPA, CA, MTax, is an award-winning professor at the Schulich School of Business at York University and an independent tax advisor.
Haroon Khan, CPA, CA, is a seasoned tax professional with over 15 years of experience advising private corporations on tax planning, mergers & acquisitions, and cross-border structuring.




(0) Comments